


We believe the global economy still treads a relatively narrow path with modest, largely sub-trend growth, being reported in the data in many areas, but with forward-looking indicators being generally positive, suggesting some acceleration. However, risks remain, with those to the downside likely to be predicated on the potential for re-escalation of hostilities in the Middle East and elsewhere, or their potential emergence in other spheres. To the upside, it is likely that a resolution to the Iran conflict that allows for a greater flow of oil through the Strait of Hormuz, could have positive effects on the prospects for energy prices and by extension, on growth and interest rates. Although inflation is generally above the respective target levels for the central banks across the world, particularly among developed economies, we envisage modestly higher interest rates and an eventual reduction in longer-dated bond yields. The political landscape ahead presents a number of events, such as the US midterms in November and the French presidential election in the first half of 2027, any of which may have the capacity to create new potential concerns for asset and currency markets.
Quarterly fixed income review and outlook
Quarterly fixed income review and outlook
Our quarterly review and outlook provides a summary of key market changes before offering a more detailed look at our global and regional economic views, as well as our views on specific asset classes including investment grade and high yield debt, emerging market debt, secured finance, municipal bonds and currencies.
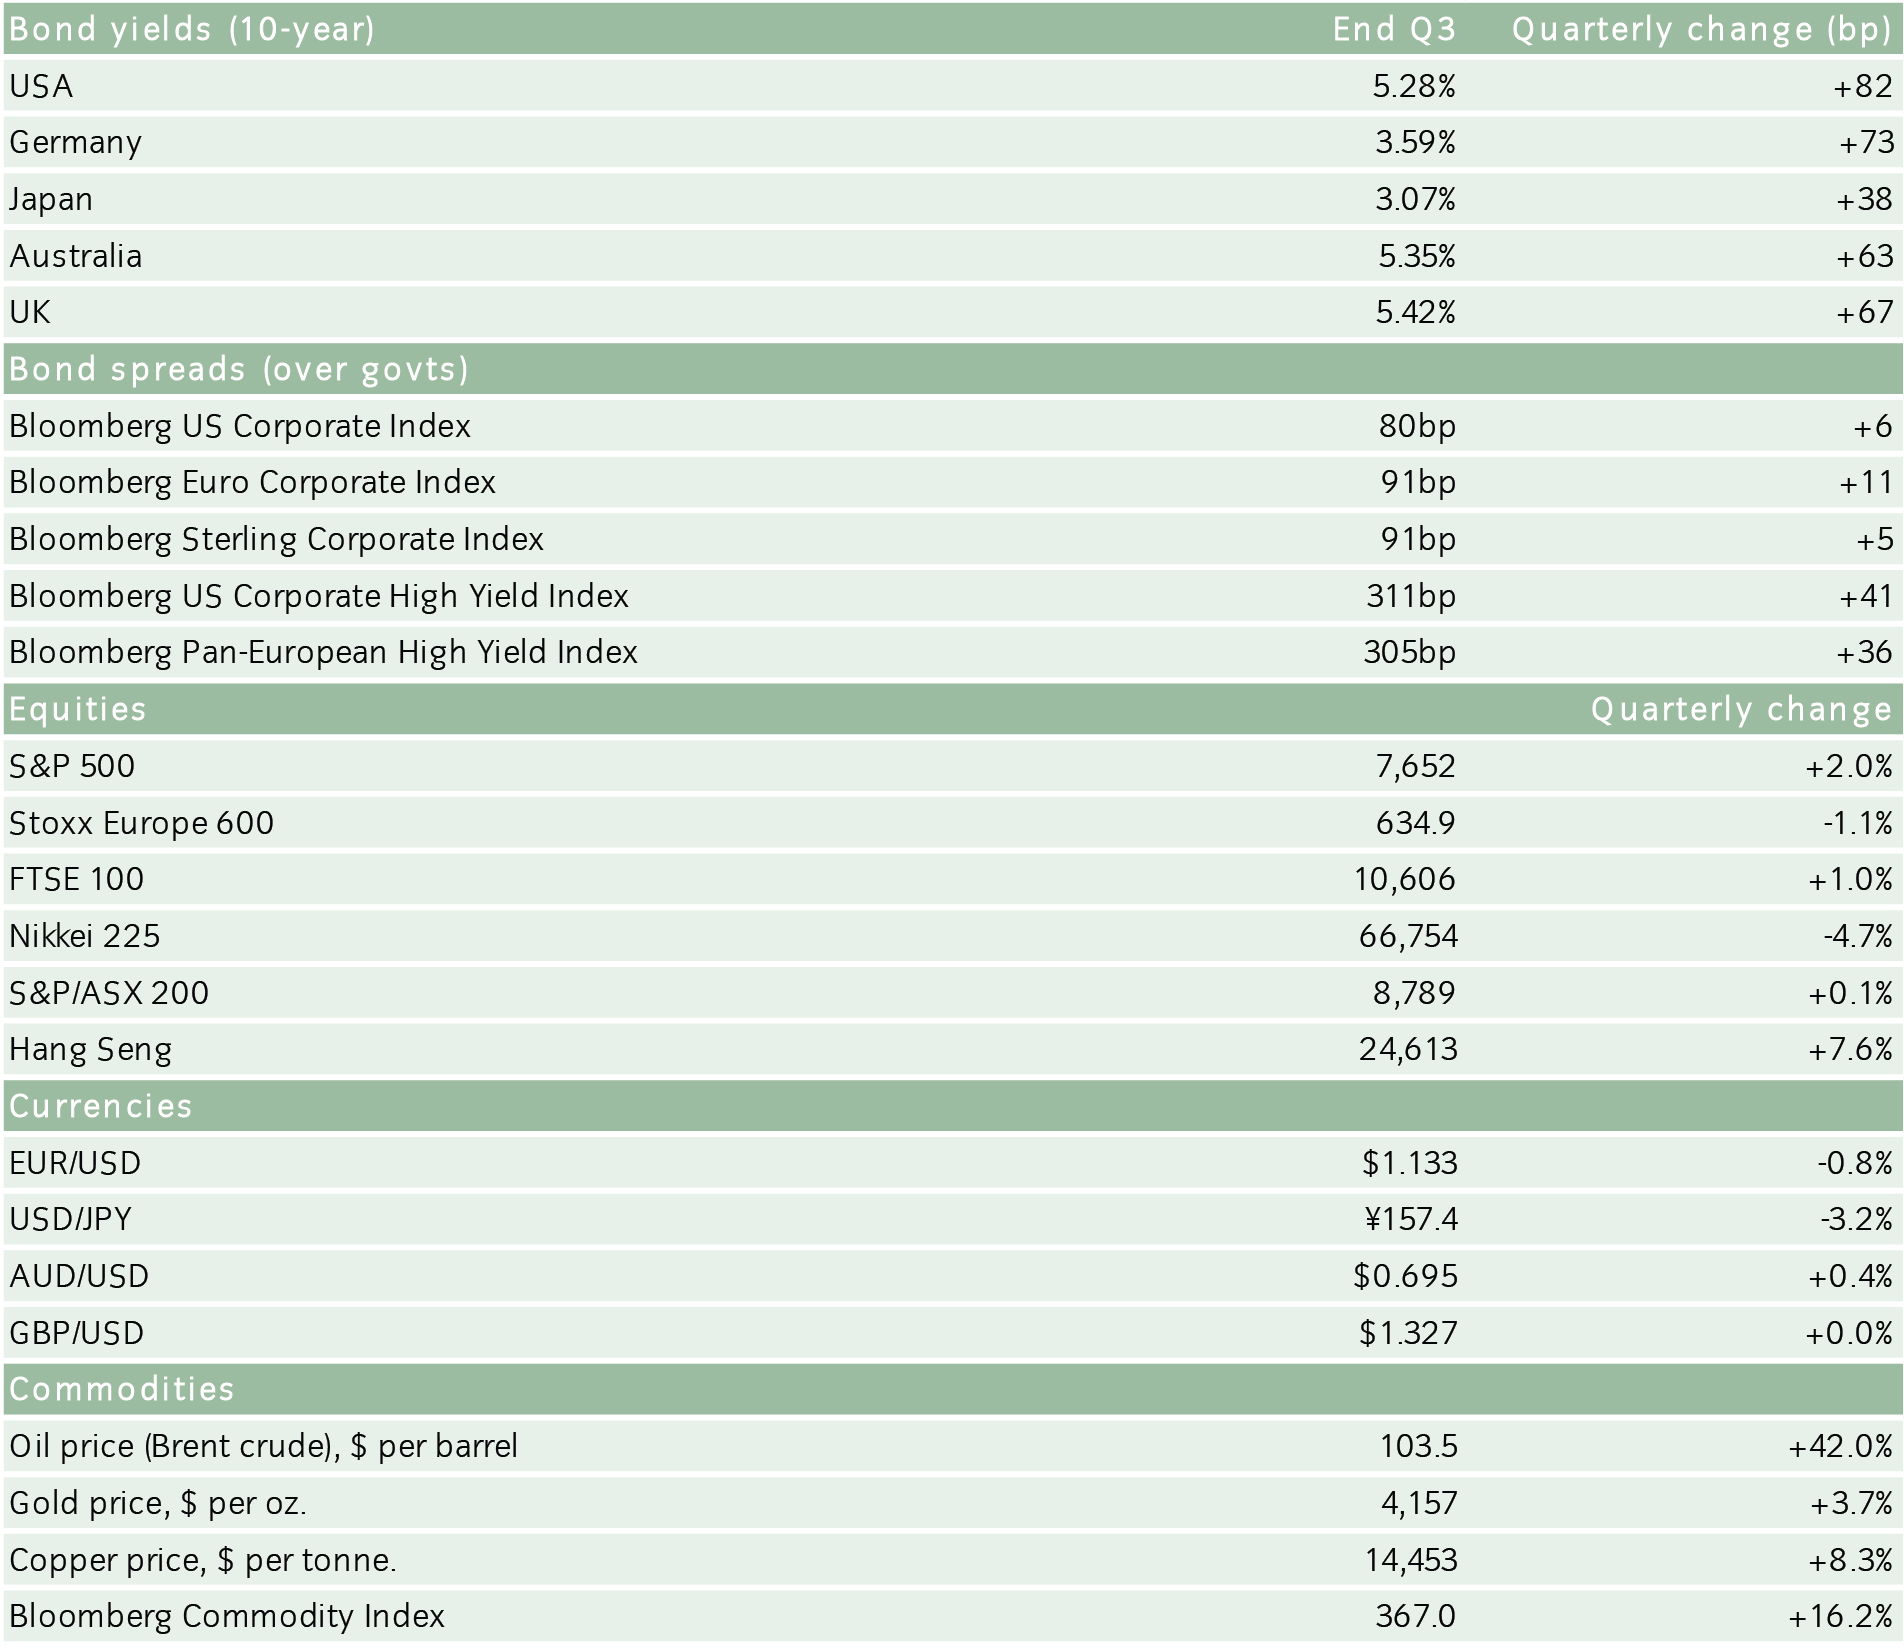
Source: Bloomberg. As at 30 September 2026.
Economic outlook
We continue to maintain a fairly benign outlook for the US economy, and we think that a combination of an expansionary fiscal policy and the ongoing AI-investment cycle are likely to serve as supportive tailwinds. However, the composition of the economy does appear to expose the broader recovery to some fragility. The concentration of wealth among the richest of the population supports spending by that group, while income growth among the remainder is relatively lacklustre. The supportive economic drivers face a potential counterweight in the form of a sustained oil shock, which pushes the near-term balance of risks to our growth forecast to the downside, and those to our inflation forecast to the upside. Overall, we expect GDP growth to remain at of just above 2% per annum for 2026 and 2027, marginally below what may be regarded as the trend rate. Inflation is likely to pass its peak in coming months, leaving the overall headline rate for 2026 at around 3.4%, before declining back towards the Fed’s target rate, with 2027 inflation at 2.5%. Having recently raised interest rates, we anticipate further Fed rate hikes to be implemented in the course of coming quarters, taking the Fed funds rate to the 4.5%-4.75% range. There are clear risks to all forecasts, ranging from the potential for positive developments that may arise from a successful resolution to the war in the Middle East, to potential further downside should hostilities there or in Ukraine re-escalate. In addition, the midterm elections in November may introduce further uncertainty on policy. With higher short term interest rates anticipated, we believe Treasury yields may remain more elevated than previously and now see 10-year yields declining only to around 4.55% in the next year, and with yields at shorter maturities remaining above 4.25%.
Prospects for economic growth in the eurozone remain muted, particularly in comparison to the US. Our forecasts for GDP growth are marginally below the consensus as we see it being below 1% in 2026, before reaching that level in 2027. That anaemic expansion comes despite the anticipated fiscal spending in Germany. Risks to that remain, particularly if the Ukraine conflict was to worsen once more or further flashpoints developed. We see eurozone inflation being 2.8% this year before easing back to 2.3% in 2027, closing in on the ECB target of 2% more consistently in the latter part of the year. To achieve that objective, we see the ECB raising interest rates once more, taking the deposit rate 2.75%. As inflation reaches its target in a year’s time, we believe that the central bank is likely to unwind that hike, so that rates are at the same level as they are currently. As bond yields have risen in recent weeks, we believe that although most of the increase can be reversed, 10-year yields will remain above 3% at around 3.10% in 12 months. Shorter-dated yields may decline by more particularly once it becomes clearer that policy rates have peaked. Challenging fiscal issues may create additional volatility in bond yields, with France notably vulnerable given the debt and deficit levels the fragile government faces, and with the presidential election looming in the first half of 2027.
Our expectations for UK economic activity are for GDP growth to be just in excess of 1% in both 2026 and 2027. Both rates of expansion are well below what is regarded the trend rate of growth. However, the ongoing uncertainty about oil and other energy prices, driven by the stand-off lack of resolution in the Middle East conflict, means inflation is expected to remain above the target level of 2% set for the Bank of England, and be close to 3% in 2026. Into 2027, we see the headline rate declining only slightly, to 2.6%. Significant focus remains on the outlook for public finances and the debt burden, which has been putting upward pressure on gilt yields, as the market expresses its concerns about both inflation and the public deficit. We see the Monetary Policy Committee eventually conceding that interest rates need to be raised and expect it to hike rates twice over the next year, taking the Bank Rate to 4.25%. Gilt yields are likely to moderate gradually, with the 10-year yield declining back below 5%, to around 4.90% in the next year.
In China, GDP growth of 5% in 2025 is unlikely to be repeated in either 2026 or 2027. We forecast 4.0% expansion this year and 3.6% growth next year. As has been the case for some time, domestic growth is expected to struggle, despite official internal efforts to encourage it. The housing market remains soft, with prices for new homes still declining and with little expectation for that trend to reverse for some time. The external sector remains the main engine of economic growth despite the backdrop of US tariffs, supported by the expectation that global AI-related and tech-based investment spending will continue. With overall growth expected to remain sub-par, particularly in the domestic economy, we do not see inflation gaining much momentum, with headline inflation being 1.4% in 2026 and 1.5% 2027. During that time, we do not expect the People’s Bank of China to make changes to short-term interest rates.
In other emerging markets, we see modest expansion rates in excess of the US and other developed markets, but we expect external conditions will have diverging effects in different economies. Energy exporters will continue to benefit as long as oil prices remain elevated, while energy importers suffer. Prospects for inflation may remain elevated though, which could pose a barrier to central banks having freedom to implements substantial reductions in interest rates, which remain high in many areas.
Asset class outlook
The investment grade credit market remains finely balanced; on one hand credit spreads are still close to post-global financial crisis tights despite heighted geopolitical uncertainty and yet look more attractive when considering value from an all-in-yield perspective. New issuance remains elevated, driven largely by a wave of issuance from hyperscalers but has been matched by investor demand that continues to be supported by strong corporate earnings growth. Some hyperscalers have started to supplement debt funding with equity issuance, partly easing concerns around rising leverage levels.
Given the scale of issuance seen so far this year from the broader market, we believe some financing activity has been brought forward, which could result in better technical dynamics into the year-end. From a fundamental perspective, corporate balance sheets are underpinned by robust and broad-based earnings growth, healthy liquidity positions and continued access to capital markets. So, while valuations remain rich, it’s difficult to see meaningful softening in demand for investment grade credit with supportive all-in-yields, supportive fundamentals and a resilient economic outlook. We therefore believe this supports a modestly constructive outlook for credit markets, with a focus on bottom-up security selection.
Despite ongoing geopolitical tensions, inflation uncertainty and interest-rate volatility, we remain broadly constructive on high yield markets. Attractive all-in yields, resilient corporate fundamentals and strong corporate earnings and revenue growth are underpinning demand. Spreads widened in Q3, with a sharp selloff in lower rated credits. This came despite a generally positive outlook for future earnings for the asset class as a whole and high interest coverage levels that suggest many companies could weather a higher rate environment. Although we continue to be cautious on CCC-rated names, we believe this offers an attractive entry point for higher rated issuers, although we continue to see income rather than spread compression as the primary driver of future returns. We also expect issuance to accelerate following the summer slowdown as companies return to both bond and loan markets, although robust investor demand should allow markets to absorb this supply without significant disruption. At the same time, dispersion continues to run at elevated levels as investors are rewarding issuers with strong balance sheets, resilient cashflows and credible deleveraging plans while penalizing those facing structural or operational challenges. Against this backdrop, we believe careful credit selection will continue to be important. While we believe high yield markets continue to offer compelling income opportunities, future performance is likely to depend on identifying and avoiding issuers facing business model disruption or deteriorating fundamentals.
Many emerging market central banks face less pressure to tighten policy than their developed market counterparts, so we believe they can therefore afford to remain more patient with inflation. Consequently, we remain constructive on emerging market local rates, with our preferences concentrated in several idiosyncratic country positions where domestic developments are expected to play a greater role than moves in developed market rates. Countries where those characteristics may remain appealing include Colombia, Turkey, Argentina and Brazil. The high level of interest rates reflect tight monetary policy in Turkey, which we find encouraging as a sign of the adoption of a more orthodox monetary policy framework, which supports the prospect of continued disinflation. We also believe the emerging market corporate sector has some supportive features in its favour. The asset class continues to benefit from what we see as steady investor inflows, limited net issuance and a supportive macroeconomic backdrop. Relative to developed markets, fiscal concerns are generally less pronounced. With the overall emerging market space, we retain a preference for high yield over investment grade, primarily given the additional spread compensation available and the more attractive relative-value opportunities we are seeing within the higher-quality segment.
Economic data across both the US and Europe has continued to demonstrate remarkable resilience, with labor markets remaining healthy and consumer spending broadly supportive of growth. Corporate fundamentals also remain broadly stable, supported by solid earnings, healthy balance sheets and continued access to capital markets. Against this backdrop, demand for the asset class has remained robust, driven by both attractive income levels and its defensive characteristics. The predominantly floating-rate nature of the market means investors benefit from any further rate increases. In an environment where longer-dated bond markets remain sensitive to concerns around inflation and fiscal deficits, the asset class potentially offers a relatively insulated means of generating income without taking significant duration risk. Given the strength of investor demand and the favourable financing environment, we would expect primary market activity to pick up into the end of the year. Our focus remains on senior, well-protected parts of the capital structure, prioritizing transactions with robust underwriting, strong servicing and structural protections that preserve cashflows in downside scenarios. We believe this positioning should help insulate portfolios from ongoing macro, inflation and geopolitical uncertainty, while allowing us to pursue attractive income and relative-value opportunities.
Municipal market conditions remain challenging. Recent underperformance has driven mutual fund outflows, amplified by tax-loss harvesting, persistent interest-rate volatility and quarter-end positioning, while a heavy supply calendar has added further pressure to valuations. These weak technicals may continue until rates become more stable. However, the asset class is now offering historically attractive taxable-equivalent yields, and we believe what we see as compelling income levels should eventually draw investors back once volatility subsides. Combined with the sector's generally strong credit fundamentals, this could support a meaningful improvement in demand and market technicals over the medium term.
Currency markets continue to be influenced by diverging growth and inflation dynamics. While global growth remains broadly resilient, higher energy prices and the resulting repricing of US interest rates have supported the US dollar, reinforced by the US's status as a major energy exporter. However, we remain mindful of longer-term headwinds for the dollar stemming from fiscal concerns and policy uncertainty. In contrast, the euro faces a more challenging backdrop as higher energy costs and weaker terms of trade weigh on the growth outlook, although persistent inflation and a relatively hawkish ECB provide some support. Beyond the US dollar and euro, energy prices remain an important driver of currency performance. The Japanese yen has continued to face pressure from higher energy import costs, although intervention by policymakers and the prospect of tighter monetary policy could provide support if accompanied by a shift in domestic investor allocations. Meanwhile, commodity-linked currencies such as the Norwegian krone and Canadian dollar have benefited from stronger energy prices and improving economic fundamentals, while traditional safe-haven currencies, including the Swiss franc, may remain driven more by shifts in global risk sentiment than by interest rate differentials.


